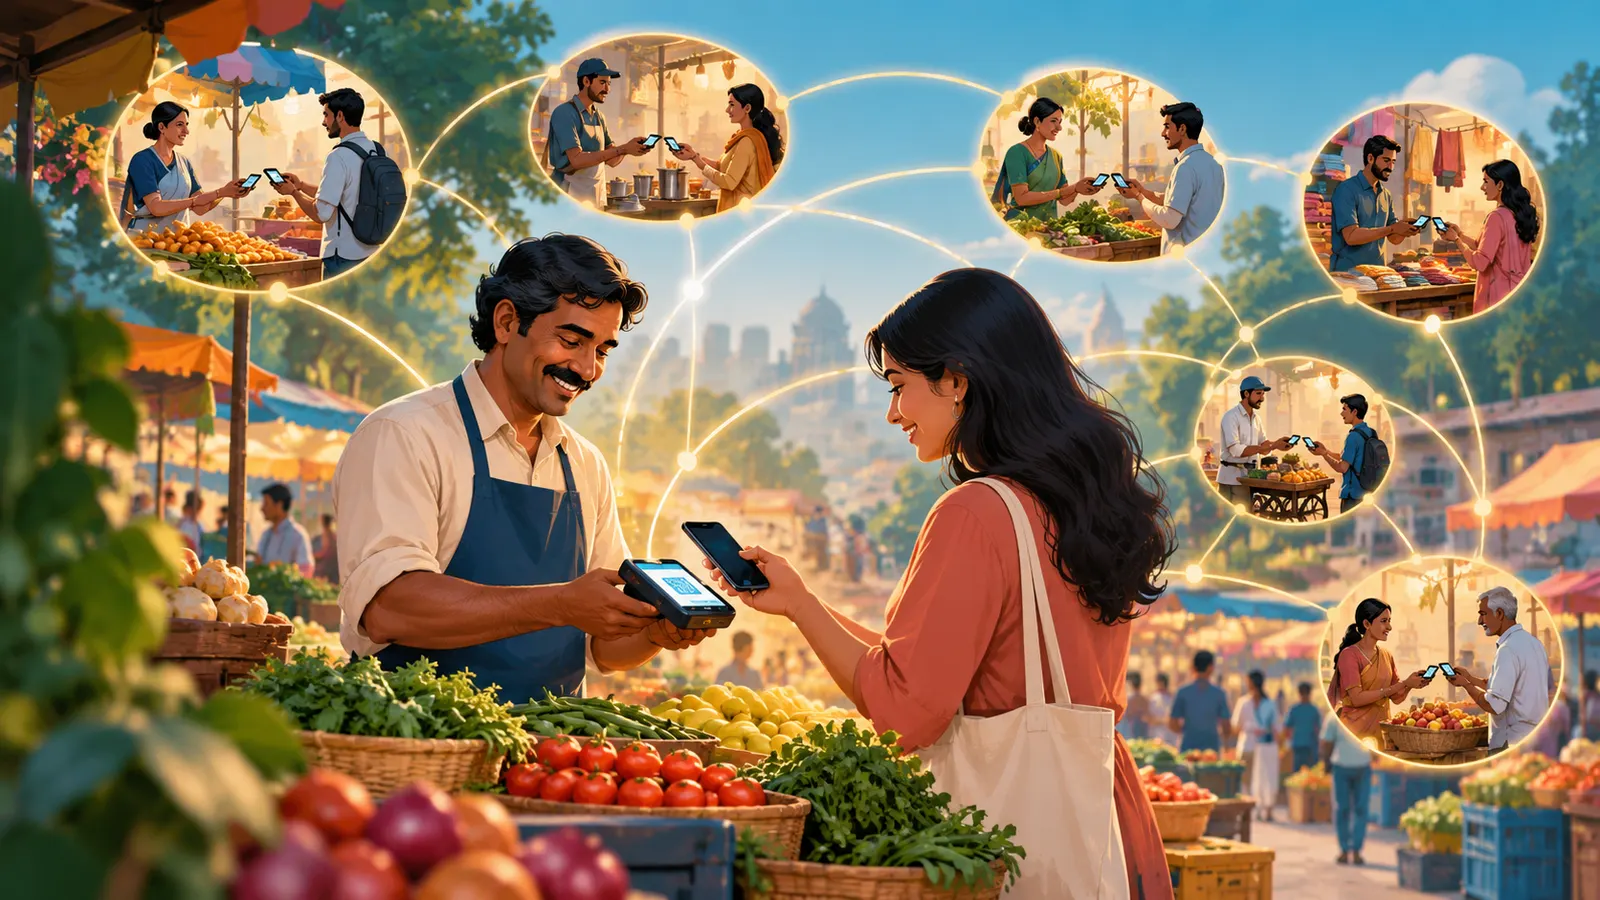
India's Unified Payments Interface has made the transfer of small amounts of money an ordinary part of daily life. The National Payments Corporation of India's public statistics continue to record very large transaction volumes in 2026. The numbers can encourage a simple story of technological success. Yet a payment system is more than the action of scanning a code. It depends on shared rules, banks, merchants, reliable connections, and people's confidence that a transfer will arrive and can be checked.
Before discussing its economic effects, distinguish a transaction count from the value transferred. Many small payments can produce a high count without representing the same total value as fewer large payments. Growth in digital payments may also replace cash transactions rather than create new purchases. The count tells us that a method is being used; it does not on its own show that national income has risen or that every participant is better off.
For a small merchant, a convenient payment option can reduce the friction of making a sale. Customers need not have exact change, and a record of receipts may be easier to maintain. But convenience also introduces dependencies. A network outage, a failed notification, or uncertainty about whether money was credited can disrupt a busy hour. The system's usefulness depends not only on average speed but on predictable support when a transaction goes wrong.
Trust is built through ordinary details. A clear confirmation screen, a way to review past payments, and a credible process for reporting errors matter because most users cannot inspect the underlying banking infrastructure. The speed of a successful transaction attracts attention; the handling of a failed one determines whether someone will continue to rely on the system. Payment technology must be judged over the entire experience, including dispute resolution.
Interoperability is another part of the achievement. If customers and merchants had to use the same provider for every transfer, a popular service could lock users into its own network. Shared payment rails make it easier for different applications and financial institutions to connect. That design can support competition at the level of the user interface while preserving a common route for the transaction. It also raises questions about how costs of the shared infrastructure are covered.
Digital records may help a business understand its sales, but they can also change its relationship with lenders, platforms, and tax systems. A record is not automatically a fair measure of business health: seasonality and cash transactions may still matter. Some merchants may welcome formal records; others may worry about costs or the use of their data. A public discussion should avoid treating every objection as hostility to technology. Adoption affects a person's exposure to institutions as well as their convenience.
Access remains uneven. A person may own a phone but face unreliable connectivity, limited digital literacy, or difficulty reading an application's language. Older users may depend on others to complete a payment, creating risks of confusion or exploitation. If cash becomes harder to use before reliable alternatives are available, a tool intended to widen participation can exclude some people. A resilient system gives users workable options during failure and transition.
Payment systems also concentrate attention on fraud. A transfer can be easy to initiate and difficult for a deceived user to reverse. Clear warnings and verification procedures can help, but they should not require every customer to become an expert in financial security. The distribution of responsibility matters: banks, app providers, merchants, and users each control different parts of the process. Effective protection requires coordination rather than blaming the last person who touched a screen.
The broader lesson is that a smooth digital action rests on collective infrastructure. The technology may save seconds at the counter, but its economic value comes from being widely usable, trusted, and dependable. A rising transaction count is evidence of reach. To judge the quality of progress, ask whose payments fail, how problems are resolved, what alternatives remain, and whether small participants gain bargaining power rather than merely becoming visible to a larger system.